

EU handling fee: 2 € per item on parcels from outside the EU
From 1 November 2026, the EU applies a 2 € handling fee per distinct item to e-commerce goods from outside the EU. How it adds up, who pays and what to check.
- The Commission and customs say that from 1 November 2026, online sales shipped to EU consumers from outside the EU carry a 2 € fee per distinct item.
- It comes on top of the 3 € duty per item that generally applies up to 150 €. In Revenue’s example, three different items pay 15 €, plus any VAT.
- Both charges fall first on the declarant: usually a platform, seller, carrier or agent. The fee is not refundable, even for faulty goods.
- From 1 July 2028, normal customs duties are due to replace the flat 3 € duty, and the EU Customs Data Hub becomes mandatory for e-commerce.
What the EU handling fee is, and when it starts
From 1 November 2026, the EU will apply a new Union handling fee of 2 € per distinct item. It covers online orders shipped to EU consumers from outside the Union. The date and the amount come from the European Commission and from national customs authorities such as Revenue in Ireland and Dutch Customs.
- DEFINITION Union handling fee
- A fee of 2 € per distinct item in a package. It applies to all e-commerce goods shipped from outside the EU to a consumer in the EU, including those worth more than 150 €.
The fee is separate from, and in addition to, the 3 € customs duty per item that has applied since 1 July 2026 to parcels worth up to 150 €. The Commission says that duty “levels the playing field” for all businesses bringing goods into the EU market. According to the Commission, the handling fee is meant to cover the increasing costs customs authorities face with small parcels: checking the data, risk analysis, and documentary or physical controls when needed.
The 2 € amount is set by a Commission delegated regulation of 21 September 2026. It supplements the new Union Customs Code, Regulation (EU) 2026/2108, published in the Official Journal of the European Union on 19 September 2026.
What counts as an item
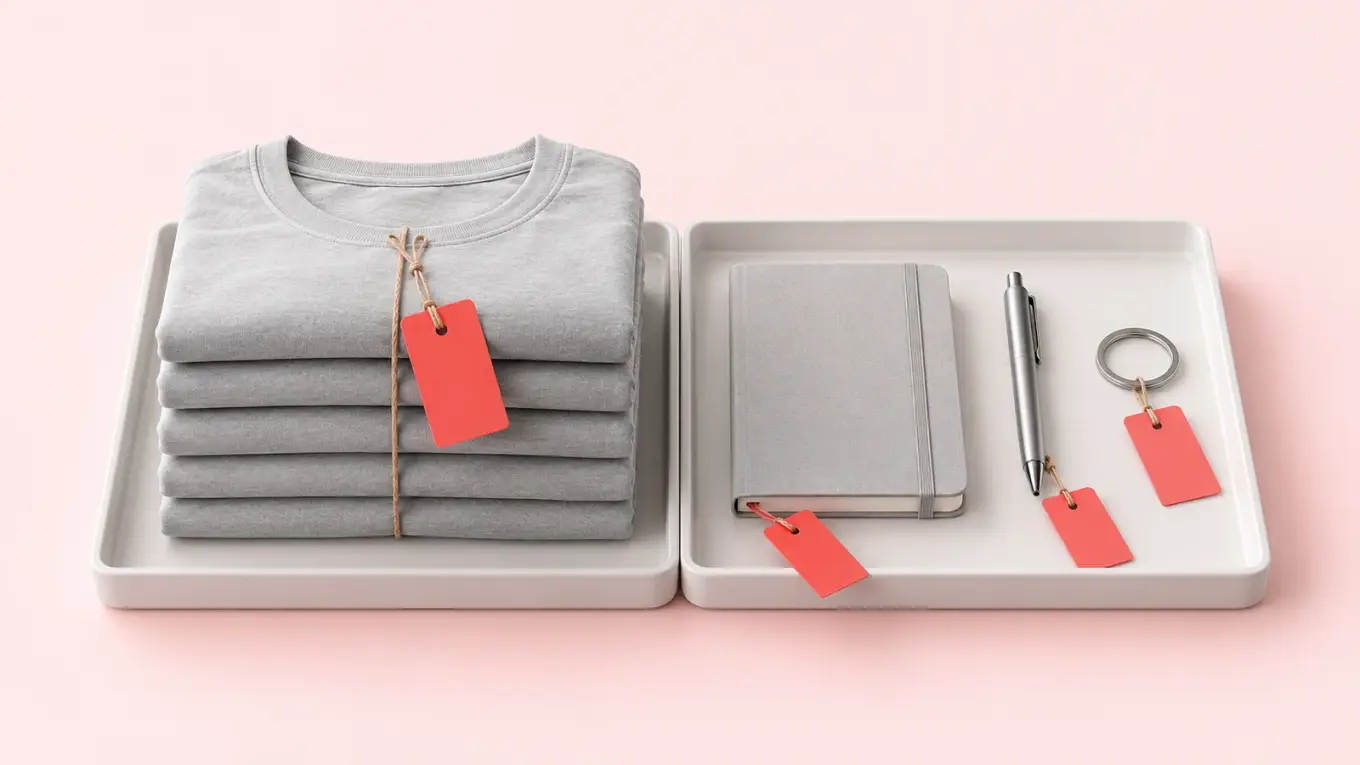
The fee is charged per distinct item, not per parcel or per unit. Revenue gives an example: two identical pens in a package count as one item, while a pen, a notebook and a keyring are three different items.
Dutch Customs counts the fee per declaration line: in its example, 2 shirts, 3 sweaters and 1 hat make 3 declaration lines. The Commission’s guidance gives the rule behind it. An item is all the goods in a consignment that share the same tariff classification, description and, where required, origin.
The 3 € customs duty is also counted per item. The Commission says it applies per item in a consignment, based on tariff classification and not on quantity, and gives two examples:
| Consignment | Items counted | 3 € customs duty |
|---|---|---|
| 5 T-shirts | 1 | 3 € |
| 1 T-shirt and 1 watch | 2 | 6 € |
How the 2 € fee and the 3 € duty add up
As a general rule, on a parcel worth up to 150 €, both charges apply item by item. The 3 € duty applies from 1 July 2026 until 1 July 2028, and the 2 € handling fee comes on top. Revenue’s worked example shows the result for a low-value parcel with three different items.
9 € Customs duty, 3 × 3 € 6 € Handling fee, 3 × 2 € 15 € Total charges + any VAT
A pen, a notebook and a keyring count as three distinct items. Any applicable VAT comes on top and is not calculated here.
Source: Revenue (Irish Tax and Customs), 29 September 2026
Above 150 €, the flat 3 € duty does not apply: the ordinary duty rate for each product applies instead, and the 2 € fee per item still applies. In a second Revenue example, a parcel worth more than 150 € holds jeans and trainers. Each pays its own duty rate, and the handling fee adds 4 €, plus VAT.
For goods that qualify for preferential tariff treatment under a trade or customs union agreement, the declarant can claim that preference instead of the flat 3 € duty. This needs a full customs declaration (H1) and is only possible when IOSS has not been used to collect the VAT. According to the Commission’s guidance, these goods still pay the 2 € handling fee.
Two charges, both per item: as a rule, the 3 € duty on parcels up to 150 €, and the 2 € handling fee at any value.
Who pays, and which sellers it affects
The Commission’s guidance puts both charges first and foremost on the declarant: the platform, seller, carrier or agent that declares the goods to customs. National customs authorities describe who pays the fee in similar terms:
| Source | Who pays the 2 € handling fee |
|---|---|
| European Commission | The declarant, who is also the main debtor of the 3 € duty. Where IOSS is used, that is the IOSS holder or its indirect representative. |
| Revenue (Ireland) | The e-commerce seller or the business delivering the goods. |
| Dutch Customs | The declarant. |
Consumers can declare the goods themselves only as a residual option: in the few Member States with a free online declaration for individuals, and only when IOSS has not been used. A consumer who does so becomes the debtor. Revenue adds that the seller or delivery business may pass the fee on to the end consumer, at checkout or on delivery.
The fee applies to distance sales: goods dispatched by or on behalf of the seller from outside the EU to a consumer in the EU. It therefore affects merchants who ship to EU shoppers from outside the Union, for example from Great Britain or Switzerland. It also covers orders from EU shoppers sent directly from stock or suppliers outside the EU.
Whoever pays it, the fee is not refundable. Revenue says this applies even where goods are later found to be faulty. Dutch Customs adds that it is not refunded either if delivery fails or the parcel is refused or returned.
What changes in 2028
The flat 3 € duty is temporary, but the handling fee is not, according to the Commission’s guidance. The duty is due to apply until 1 July 2028, after which normal customs duties will apply to these low-value consignments. The same date matters for customs data: the EU Customs Data Hub will become mandatory for e-commerce from 1 July 2028. If the Data Hub is not ready by then, the Commission may propose extending the flat duty.
- 1 Jul 2026 Flat 3 € customs duty per item begins On consignments worth up to 150 €, per item by tariff classification.
- 21 Sep 2026 Commission adopts the act setting the 2 € fee By a delegated regulation supplementing the new Union Customs Code, Regulation (EU) 2026/2108.
- 1 Nov 2026 The 2 € Union handling fee applies Per distinct item, on e-commerce goods shipped from outside the EU to EU consumers, at any value.
- 1 Jul 2028 Normal duties due to replace the flat 3 € duty The EU Customs Data Hub becomes mandatory for e-commerce.
Source: European Commission; Revenue (Ireland); Dutch Customs
- DEFINITION Importer for distance sales
- A new role created by the EU customs reform. Online platforms that sell goods into the EU will become importers for distance sales, responsible for ensuring that duties and VAT are paid at purchase.
According to the Commission, EU shoppers will thus no longer face hidden charges when the parcel arrives. Importers for distance sales will also be the first to report their sales through the EU Customs Data Hub. The Commission adds that from 2028 the fee will be lower where the importer operates a customs warehouse, because customs checks are easier.
What to check before 1 November
These are our recommendations, not legal requirements or tax advice:
- Count items, not parcels. Both charges are per item, so look at the declaration lines in your typical EU orders.
- Ask who declares and pays. Ask your carrier, marketplace or customs agent who declares and pays in your shipping flow.
- Check preferential origin. If your goods may qualify for preferential tariff treatment, ask your customs agent whether to claim it. It is only possible without IOSS.
- Decide whether to absorb or pass on the cost. If you pass it on, show shoppers the final cost before checkout.
- Review multi-item baskets. The per-item charges weigh most on orders that combine several different low-value goods.
- Check delivery and returns information. Make sure your delivery promises and returns terms still hold for EU shoppers.
Under EU consumer rules, as summarised on the EU’s Your Europe portal, the trader must give the total price before an online order. That price includes taxes and any additional charges, such as delivery costs. The Consumer Rights Directive adds that where those charges cannot reasonably be calculated in advance, the trader must say that they may be payable.
Before the year-end peak
The fee starts a few weeks before Black Friday, so it is worth settling these questions early: see our calendar of European sales peaks. For VAT and returns, see our guide to entering a new European market. If delivery costs change, keep your shop and product feeds consistent.
From 1 November, each distinct item in an e-commerce parcel from outside the EU carries a 2 € fee, on top of the 3 € duty that generally applies up to 150 €.
Quick answers
What is the EU handling fee, and when does it start?
The Union handling fee is a charge of 2 € per distinct item on e-commerce goods shipped from outside the EU to consumers in the EU, whatever their value. According to the European Commission and national customs authorities, it applies from 1 November 2026.
How are items counted for the EU handling fee?
The EU handling fee is charged per distinct item, not per unit or per parcel. The Commission’s guidance defines an item as goods sharing the same tariff classification, description and, where required, origin. In Revenue’s example, two identical pens are one item.
How much do the EU handling fee and the 3 € duty add to a parcel?
In an example from Ireland’s Revenue, three different items in a parcel under 150 € pay 9 € of customs duty and a 6 € handling fee: 15 €, plus any VAT. Above 150 €, each product’s ordinary duty rate applies instead of the flat 3 €, and the 2 € fee per item still applies.
Who pays the EU handling fee and the 3 € customs duty?
The Commission’s guidance puts both charges first on the declarant: the platform, seller, carrier or agent that declares the goods to customs. Consumers can declare only as a residual option, without IOSS. Ireland’s Revenue adds that the fee may be passed on.
Is the EU handling fee refundable?
No. Ireland’s Revenue says the fee is not refundable, even where goods are later found to be faulty. Dutch Customs adds that it is not refunded either if delivery fails or the parcel is refused or returned.
What changes for low-value parcels from outside the EU in 2028?
The Commission says that from 1 July 2028 normal customs duties are due to replace the flat 3 € duty, and the EU Customs Data Hub becomes mandatory for e-commerce. Online platforms selling into the EU will become importers for distance sales, the first to report sales through the Data Hub.
Get the next shift in European e-commerce before it hits your numbers.
One email a month on Google Shopping, comparison sites and AI search. No spam.
Controller: Komparoo. Purpose: sending our newsletter. You can unsubscribe or exercise your rights at any time. More in our privacy policy.
Sources: European Commission (EU customs reform, with the news of 7 October 2026 on the Union handling fee), European Commission, DG TAXUD (guidance «The temporary EUR 3 customs duty and the Union handling fee», version of 5 October 2026), Revenue, Ireland (press release of 29 September 2026 on the Union handling fee), Revenue, Ireland (How the Union handling fee applies), Dutch Customs (Handling fee for e-commerce), European Commission (questions and answers QANDA/26/1492, 1 July 2026), European Commission (guidance and legal text on the temporary flat fee for low-value imports, 8 June 2026), European Commission (questions and answers QANDA/26/736, 26 March 2026), European Commission (press release IP/26/1904, 21 September 2026), Your Europe (E-commerce, distance and off-premises selling), Directive 2011/83/EU on consumer rights (Article 6).